
Old Glory Bank's unification of traditional banking and cryptocurrency.
We have announced our plans to bring together legacy finances and future currency technology in one dashboard.
Cryptocurrency and stablecoins are the culmination of everything we have been fighting for - the Privacy, Security, and Liberty you and your finances deserve.
Old Glory Bank's NxtGen Banking
In Episode 7 of the PSL Podcast, President and CEO Mike Ring and Old Glory Bank's Chief Innovation Officer, Michael Staw, share an update on our plans to offer customers the ability to manage crypto and stablecoins, a self-custodial wallet, and traditional bank accounts within a single dashboard.
Please watch and share it with your friends and colleagues who are as excited as we are about the next generation of finance.
Freedom to Choose
At Old Glory Bank, we see the evolution of banking – the incorporation of cryptocurrency, stablecoins, and self-custodial wallets – as the culmination of everything we have been working for: your Privacy, Security, and Liberty in banking.
Your freedom to choose between traditional banking and legacy currency, and digital currency is part of that autonomy. Many of you have been eager for this merger of old and new, and it's finally here.
Others of you have no interest in crypto and digital currency, and that's ok, too. We will continue to offer both, so that your liberty is protected. We stand with you.

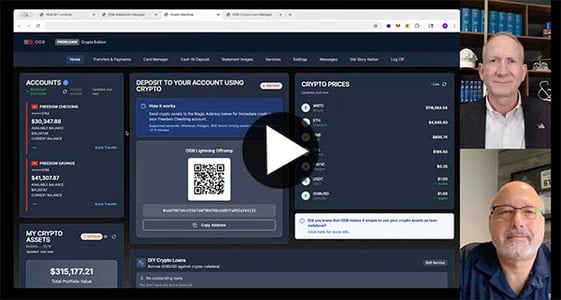
Watch the Demo
We believe Old Glory Bank will be the first bank to easily link your crypto, stablecoins, and self-custodial wallet into a single dashboard, combined with your OGB Accounts. Once linked, you can easily “on-ramp” and “off-ramp” US Dollars (fiat) with popular crypto coins, creating a seamless experience to spend fiat and crypto every day.
OGB Customers will be able to use our new stablecoin, OGBUSD, for payments and remittances around the world. Recipients can hold it, spend it, exchange it for U.S. dollars at Old Glory Bank, or convert it on any exchange supporting ERC-20 standard tokens.
OGBUSD will be backed by US Dollars, 1 to 1, so you will always know the value and buying power.
Cryptocurrency 101: Terms to Know
Crypto fans and experts, you can skip to the next section.
If you are just learning about crypto, you might find this glossary helpful.
Cryptocurrency
A type of digital money. Unlike dollars, it doesn’t exist in physical form and isn’t controlled by a government or bank. Instead, it’s powered by blockchain technology.
Popular cryptocurrencies include:
- Bitcoin (BTC) – the first and most well-known
- Ethereum (ETH) – used for smart contracts and NFTs
- Solana, Cardano, Dogecoin – other coins with different purposes
You can use crypto to buy things, invest, or even support creators online.
Stablecoin
A type of digital currency that is pegged to the value of a stable asset, such as a fiat currency like the U.S. dollar. Its purpose is to combine the benefits of cryptocurrency, like fast, borderless transactions, with the price stability of traditional money.
Old Glory Bank plans to mint our own stablecoin, OGUSD, with the release of our crypto features in early 2026.
Fiat
Government-issued currency that is not backed by a physical commodity, like gold or silver, but rather by the government's declaration that it has value. Examples include the U.S. dollar (USD) or euro (EUR).
When used in digital finance, fiat currency typically refers to traditional money that can be transferred electronically, such as through bank apps, payment platforms, or converted into stablecoins.
Key
A crypto key is a fundamental part of how cryptocurrencies and blockchain technology work. It's a piece of cryptographic information used to secure, access, and control digital assets.
A private key is a string of letters and numbers used to sign transactions and prove ownership of a crypto wallet. It must be kept secure and never shared - sharing your private key is like handing your actual physical wallet to a crook and inviting them to clean out your cash.
A public key is derived from your private key using cryptographic algorithms. It can be shared with others safely, often to allow you to receive cryptocurrency.
Think of your public key as your email address (you can share it) and your private key as your email password and PIN (you must keep it secret).
Gas
In cryptocurrency, gas refers to the fee required to perform a transaction or execute a smart contract on a blockchain network. The gas fee is the amount of cryptocurrency you must pay to process your transaction. The amount of gas required depends on the complexity of the transactions, the congestion of the network, and the price of the gas itself.
Blockchain
A digital ledger – a record of transactions – that is:
- Decentralized: No single person or company controls it
- Transparent: Everyone can see the history of transactions (but not your identity)
- Secure: Once something is written, it can’t be changed
Blockchain works by keeping the record of transactions across a decentralized and encrypted network of computers, so the data is secure, verified, and permanent.
Token
A digital asset issued on a blockchain. This can represent currency, ownership, or access rights.
On-ramp and off-ramp
In the context of cryptocurrency, on-ramps and off-ramps refer to the services and platforms that allow users to move between traditional currencies ("fiat" such as US dollars) and digital assets (like Bitcoin or Ethereum).
An on-ramp is a service that lets you buy cryptocurrency using fiat currency. It's your entry point into the crypto world. An off-ramp is a service that lets you convert cryptocurrency back into fiat currency.
DeFi
Short for Decentralized Finance, DeFi refers to a movement within the cryptocurrency space that aims to recreate and improve traditional financial systems – like lending, borrowing, trading, and investing – using blockchain technology and smart contracts, without relying on centralized institutions.
Key features:
- No intermediaries: Transactions are peer-to-peer, governed by code instead of companies or governments.
- Smart Contracts: Automated agreements that execute when predefined conditions are met, such as a transaction or event.
- Open Access: Anyone with a crypto wallet can participate without credit checks or paperwork.
- Transparency: All transactions are recorded on public blockchains. Your identity is private, but your transaction is recorded and verified.
Self-Custodial Wallet
Also known as a non-custodial wallet, this is a type of cryptocurrency wallet that gives users full control over their private keys and digital assets stored on a blockchain network.
Unlike custodial wallets, such as those offered by and controlled by crypto exchanges, no third party holds your keys. This means that only you can access and manage your funds. Self-custodial wallets typically do not require you to share your personal data, so your privacy is protected. With direct blockchain access, you can interact directly with decentralized applications and platforms ("DeFi").
Smart Contract
A self-executing program stored on a blockchain that automatically enforces the terms of an agreement when predefined conditions are met. It is the digital version of a traditional contract, but without the need for intermediaries like attorneys, banks, or brokerages.
FAQs about Old Glory Bank's Next Generation of Banking
Find answers to Old Glory Bank's specific plans and how we are building our unified dashboard.
We will have an update posted here soon, and we expect Q1 of 2027.
Our great unified dashboard, which lets you view your crypto prices and your self-custodial wallet, will be available in phase one. You’ll be able to move money on and off the blockchain, use our stablecoin, and we will have liquidity access lines set up. Phase two will include stablecoin as a service and our custodial wallet.
Please stay tuned for more announcements! We are working as quickly as we can responsibly to launch these and other initiatives.
For today, please use your Old Glory Bank accounts as you always have, and we will let you know when this platform is ready.
Definitely not! We believe in giving our customers the freedom of choice. With Old Glory Bank, you will have the freedom of choice between using traditional bank accounts, crypto, or both.
No, the beauty of our NxtGen product will be the unity of crypto and daily banking in a single app. Those customers who wish to use only the traditional banking features will be able to, and those who choose to use the crypto features can do so as well. Freedom of choice!
The initial launch will support ETH mainnet, Polygon, PulseChain, with the possibility of additional EVM chains. XRP and BTC will be fast followers.
We’re also developing a seamless stablecoin on-ramp and off-ramp that lets you move funds directly to and from your Old Glory Bank account, without the hassle of third-party DEXs or untrusted connections. You will be able to do all of this using either the Freedom Checking or Premium Checking account, so please choose the one that fits your needs best.
OGB will offer crypto exchange services directly in our online banking app, allowing you to trade various crypto assets easily and across chains.
At launch, we will have wallet-linking capability, allowing you to trade from your own self-custodial wallet, and our own custodial wallet solution will launch shortly thereafter.
With regard to ISO20022, there are no such events emitted by OGB crypto transactions.
Finally, with regard to XRP, we use the Ripple Rails for XRP transactions, but other transactions can ride a variety of rails according to need.
The initial launch will support ETH mainnet, Polygon, PulseChain, with the possibility of additional EVM chains. XRP, and BTC will be fast followers.
So, the answer is yes, but not on the initial launch.
The OGUSD stablecoin is backed dollar-for-dollar (i.e., no fractional shares). A dollar-backed stablecoin cannot lose value, except to the extent inflation impacts all US currency. OGUSD is like "cash." A dollar-backed stablecoin makes it easy to remit payments, but we do recognize it is not a hedge against inflation. The purpose of OGUSD is to make payments anywhere in the world and fly over the top of the Federal Reserve and the SWIFT platform. But a stablecoin is not an investment asset and is not a hedge against inflation.
OGUSD is primarily different from a CBDC in that 1) it is not issued by any government or government agency, and 2) there is no centralized government control of it. The key implication is that even though transactions are visible on-chain, your ID and its association with your wallet can remain private. In terms of interchangeability, OGUSD is freely tradable and can always be redeemed at a guaranteed 1:1 through your OGB account. And as an ERC-20 token, you can swap it for other tokens on exchanges or through our interface at very low swap fees.
Lastly, the bank does not approve OGUSD transactions. It’s your money. You spend it as you choose.
Our on-ramp and off-ramp solutions are designed to move funds to and from fiat and require an OGB bank account. Of course, we do have free accounts!
We will have all the advanced security protecting your accounts, just as we do today with your traditional bank accounts. With regard to your personal crypto wallet, no one should ever need or want the keys to your wallet, including any bank. So if you choose to use a self-custodial wallet, which we recommend, we have no power to access that wallet whatsoever. The security is well within your control.
When it comes to custodial wallets you have with us, we are working on security protocols now, which will give you the same level of security you expect and deserve from any bank. We designed NxtGen Banking to be used with a self-custodial wallet, which is much more secure than an omnibus wallet, as many other organizations use.
Regarding protection against search and seizure or government freezing accounts? We will hold to the same standard we do now, which is pushing the limits to the extent permitted by the Constitution and the law. We are a law-and-order bank. We frequently push back on subpoenas, and we will not willingly give up a customer’s data. But we will always operate lawfully. When it comes down to it, you have to trust that your bank has your back, knows the law, and isn’t afraid to push back on unlawful overreach.
There is no conversion process or conversion tool. We recommend that you use a self-custodial wallet and keep your keys private; we do not have access to your crypto account. Thus, even if hacked (which is extremely unlikely given our advanced security protocols), we cannot leak what you have not shared.
We are working on a custodial wallet solution as part of our crypto solution. Our crypto services will be compatible with your cold wallet as well, which we recommend for the best security.
There is no requirement to use our stablecoin, but we think you’ll want to take advantage of the low friction in using it for on-ramping and off-ramping.
There will be no minimums, but large transactions may require an approval.
Yes, using your self-custodial wallet and, shortly thereafter, a custodial wallet. If you need treasury services, we have a “treasury management” solution in development that allows a business to hold crypto on its own balance sheet in a custodial wallet at Old Glory Bank. Although our initial launch will likely not have this ready, we predict it will be ready later in the year.
Old Glory Bank is building a best-in-class NxtGen crypto experience right inside our online banking platform. Soon, you’ll be able to view your crypto balances and activity alongside your regular accounts, simply by linking your self-custodial wallet to your online banking login. Unfortunately, currently, Old Glory Bank does not have a currency desk and, thus, we are not able to exchange or convert foreign currency. For today, we accept deposits in US dollars, so if your crypto exchange converts crypto into US Currency and ACH's currency to your account, we have no preset restrictions on crypto firms and will look at every transmitter of XRP of funds under the same color lens.
We do not have an announcement regarding gold and silver storage/conversion services at this time.
We know how big the need and opportunity are for crypto-backed lending, and we are currently building our lending solution. This will be incorporated into the second phase of NxtGen banking at OGB.
For crypto lending, collateral is held by a dedicated collateral contract which will be publicly viewable. Its assets will not be rehypothecated. In the future, we may offer loans in which we rehypothecate collateral, however, that would be a completely separate offering in which the terms are clear, and likely with a different rate structure.
It is indeed on-chain lending, and for accounts that fall within certain automatic approval parameters, it is virtually instantaneous. The rates, limits, and loan-to-value caps will fluctuate in response to market conditions.
These types of loans are asset-backed, as opposed to credit-based.
Self-loans, or liquidity access lines, will be available 24/7 for loans that fall within the auto-approval criteria and will be funded nearly instantly.
Anchorage does not offer public wallet/custody services; they only offer it for corporate treasuries. Regarding treasury services, we will have a GREAT solution, but not on day one. Standby for more information on this coming soon!
Yes, and better. We are a unified fiat and digital solution, so not only will you be able to hold your treasury assets, but you’ll also be able to do everything else that you can with a traditional bank.
Transaction times vary per blockchain. Our demo was running on Sepolia, which like Ethereum Mainnet, where our initial release will be, has a block completion time of 12 seconds, generally speaking. Since blocks complete roughly on that 12-second beat, sometimes a transaction hits the transaction queue right before the block closes, and feels instant, and sometimes it comes right after and must wait nearly 12 seconds for the next block. On a couple of those transactions, we probably got lucky. On internal transactions we generate, we use an optimized gas strategy that is extremely likely to hit the current block in progress, maximizing our chances of “getting lucky.”
On XRPL, you’re going to see reliably fast transactions, given the 3-second block time.
We are a law-and-order bank, so we are always going to follow the law. When you sell a digital asset, just like when you sell stock or land, you will be issued a 1099, as we are required to report the gross proceeds to the IRS. The solution is not to sell your crypto until you need to, so you will not have a taxable transaction.
If you send a stablecoin from one account to another account, that is not a redemption, and that happens within your own self-custodial wallet, so there is no transaction to report.
The cost of using OGB’s custodial wallet is free for customers in good standing. With regard to gas fees, there are no gas fees for transactions initiated by the bank on your behalf, including on-ramping and off-ramping (subject to daily limits). Transactions you initiate, or that require your wallet approval, will be subject to gas. For exchanges, we work to get you the best spot price, and we will make the fees visible to you before you confirm the transaction. Stablecoin generation, minting, and burning are likely to be fee-free because OGB is running these transactions from our own wallet, paying our own gas for the transaction.
We will support a very wide range of cryptocurrencies.
Our solution supports all major wallet providers.
Within our app, you can move cash to crypto and back, as well as trade between chains. However, cross-chain swaps will take longer to clear.
Yes!
On- and off-ramping is easiest through the minting/burning of OGUSD with just a couple of clicks. For other tokens, we onramp and offramp by finding the best available fill price.
The collateral backing OGUSD is USD only. Please note that we may hold some of these assets in overnights and US Treasuries with expirations of 93 days or less, but we guarantee that it is all liquid and USD.
As of today, you will not earn interest on a stablecoin because if a bank paid interest on the money backing the stablecoin, the bank would have to make money to pay that interest, which means fractional banking and risk. The GENIUS Act prohibits any issuer of payment stablecoins from paying interest or yield on those stablecoins. OGB won’t loan out the money backing your OGUSD stablecoin, which means we don’t earn interest on that money, so we can’t pay you interest.
Our stablecoin contract is a derivative of the ERC-20 standard stablecoin contract. To mint OGUSD, it’s just a couple of clicks, and transactions are generally completed within 10-15 seconds.
You can easily redeem your crypto holdings directly into your OGB account. If you need cash, we have a large network of free ATMs available.
We will have a treasury management wallet for business accounts. For example, if you are a company that creates a utility token, you will be able to store your tokens in our secure wallet.
Absolutely! We call this Old Glory Select. “One card, that’s all.” With your OGB Card, you’ll be able to decide for each purchase whether you want to spend fiat (like a debit card), use your credit line (like a credit card), or use your crypto.
Yes, but you don’t have to in order to use our crypto services. Our NxtGen solution lets you keep your coins where you want. You can either link those crypto accounts to your OGB account, or you can use our upcoming custodial wallet to transfer tokens to us.
In either case, you’ll be able to see your integrated balances right alongside your existing account, and both methods will allow you to on-ramp and off-ramp to OGUSD.
Of course. We are continually updating our training resources to help you navigate our platform, including NxtGen. We will make integrating crypto into your everyday banking experience as simple and seamless as possible!
At launch, you will not be able to use our OGB debit or credit card for crypto spending. Thus, to buy something with old-school money, you will have to move your digital assets off the chain and into fiat. Our OGB Freedom Offramp allows this to happen in seconds, without even logging into your bank account. However, later in 2027, we will launch Old Glory Select, which means “one card, that’s all.” In our app, you’ll have a slider switch, and before (or after) you use our OGB card to buy something, you will be able to select “debit,” “credit,” or “crypto.”
Old Glory Bank is a “real” chartered bank and has ALWAYS had a master account with the Fed. That is why doing business with a real, FDIC-insured chartered bank, and not a “trust” chartered organization, is so important. (Although we have nothing but love for the trust charters out there.)
For those folks who open an account with Old Glory Bank and easily connect their self-custodial wallet to our dashboard, there is no reason to send a fiat ACH transfer. Customers can move fiat onto the blockchain to mint stablecoins or buy other tokens in seconds, directly from our banking app. That’s the reason behind our NxtGen platform: there will be no need to remit fiat through third-party solutions such as ACH, wire, card networks, MoonPay, or Plaid. It’s easy to move fiat on and off the blockchain at Old Glory Bank. Your money is your business, so use the blockchain and benefit from PSL – Privacy, Security, Liberty!
Our plan is to launch our own custodial wallet by Q3 of 2027. However, we think the safest way to hold crypto is in the customer’s own self-custodial wallet. We will ultimately offer a custodial solution for convenience and treasury management. Remember, the big breaches at Binance and Drift Protocol were able to occur at this scale because customers were using the organization’s custodial wallet.
This is the reason why we are doing NxtGen banking: to make moving fiat onto the blockchain as easy as moving money from your savings account to your checking account. Your self-custodial wallet will be connected to our banking app, and you’ll move fiat to XRP (into your wallet) using Old Glory Swap in seconds!
We’ll launch with Ethereum and Solana, followed quickly (i.e., 30 days, to give our customer service team some extra time to ensure each of our customers has what they need) by BTC and the XRP Ledger.
We write our own smart contracts for our stablecoin. Where you get your stablecoin from matters, because the GENIUS Act requires ALL issuers of stablecoins in the United States to be able to “freeze, seize, and burn” your stablecoin if requested by the government. So, we ask you, who are you going to trust? Mike Ring, CEO of Old Glory Bank, has been leading the conversation on debanking and improper government snooping. We believe you should trust Old Glory Bank and its passionate patriots, including Dr. Ben Carson, John Rich, Larry Elder, and Sean Spicer. These patriots will never surrender to big government.
We’ll launch NxtGen in phases, starting with coins and tokens on the Ethereum and Solana chains, and with native BTC and XRP on the XRP Ledger quickly following (i.e., 30 days, to give our customer service team in Oklahoma some extra time to ensure each of our customers has what they need). XRP is a critical token for patriots, and we will not disappoint. Thus, once we phase in the XRP Ledger, customers of Old Glory Bank will be able to easily swap XRP for ETH, for BTC, for OGUSD, for USDC, for RLUSD, for USDT, for fiat, and then back again. That’s the purpose of Old Glory Swap.
We will maintain a liquidity pool of XRP to ensure fast swaps at the best available price via Old Glory Swap.
We agree that any remittance you want to make can be done via OGUSD, especially given our free 1-1 conversion to USDC, USDT, and RLUSD (assuming each company is in compliance with the GENIUS Act). However, we recognize that customers may want to hold ETH, WBTC, SOL, XRP, etc., for appreciation and as a hedge against inflation.
Yes! Once we phase in XRPL, you’ll be able to mint XRP from an OGB checking account, receive it in your own XRPL-compatible wallet, and then redeem XRP to get fiat back into your checking account. You keep your own keys, and there’s no need for a separate exchange account.
Even when we offer custodial services, we do not plan to stake digital assets or pay a yield. We want to provide custodial services as a convenience for customers who do not want to manage their own self-custodial wallet (although we believe they should), rather than making this a “business.”
Crypto collateralized lending is part of our launch platform and is critical for people who want to keep holding crypto while maintaining liquidity. We’ll offer loans to our customers in all 50 states at “prime,” and have the best solution out there (in our humble view).
We are not holding XRP. You are holding XRP in your own self-custodial wallet (whether hot or cold). That is our model, and we think it is always safest for customers; the breach at Binance proves us right. We are making it easy for you to move fiat on- and off-chain, directly from your FDIC-insured account at Old Glory Bank.
However, even if we decide to custody XRP, no regulatory approval is needed, because a bank is allowed to provide custodial services as part of being a bank. Granted, under the Biden Administration, the SEC was forced to make holding crypto as a custodian difficult (via SAB 121), and the FDIC was forced to punish banks under FIL16-2022. President Trump rescinded those unconstitutional regulatory letters upon returning to office.
At launch, we are not offering custody. We have been the first company to openly talk about how a self-custodial wallet is the safest way to hold digital assets. The size of breaches at Binance and Drift Protocol could only have occurred at that scale because customers held their tokens and coins in the organization’s custodial wallet. In the future, we will offer a custodial wallet for convenience, but we strongly recommend every customer hold their digital assets in their own self-custodial wallet (preferably a cold wallet) and then link it to our NxtGen app to easily move fiat on and off the blockchain.
We understand the convenience of bank custody, and we are targeting Q3 2027 for that product, but we prefer you keep your own keys so you control what leaves your wallet.
So long as it is personal business, it is personal business. The size of the transfers is not determinative. If someone is running a business and treating it as personal, we will ask them to convert to a business account.
For Bitcoin and other tokens, there is no insurance. That is why they can appreciate or decline. It is an asset, not money. However, remember that for a stablecoin, there is no need for insurance because it is backed 100% by cash or 93-day Treasuries, which is better than insurance. A bank cannot loan out or put at risk this “backing account.”
Granted, if the US dollar or 93-day Treasuries became worthless, we can be certain that FDIC insurance would also be worthless, so there is no incremental benefit to FDIC insurance over US Dollars. As a reminder, the reason a bank needs FDIC insurance is that it lends out your money through fractional-reserve banking.
Regarding your digital assets, the safest approach is to keep your own self-custodial wallet and keys. The Binance and Drift breaches show the risks of entrusting crypto to a platform’s omnibus wallet. At launch, NxtGen will let you link your own self-custodial wallet, which we believe to be the safest option against hacks (a cold wallet is best).
At launch, our OGUSD will be an ERC-20 token on the Ethereum network and on PulseChain. To the extent that your RLUSD is also on the Ethereum network, it will be easy to convert RLUSD to OGUSD. We note that some RLUSD is on the XRP Ledger, and we are phasing out XRPL within 30 days after our initial launch.
Globally, stablecoins have now surpassed ACH in worldwide volume. For cross-border payments and settlements, we believe our OGUSD stablecoin will be a highly efficient remittance solution because it is a regulated, dollar-backed stablecoin that provides an efficient, transparent, and scalable option for international payments. And if the recipient cannot convert OGUSD to a stablecoin of their choice in their local country, then they can convert to USDC, RLUSD, or USDT via our NxtGen platform (for free) and send instead of OGUSD. Meaning, because of the GENIUS Act, the world should trust every regulated US issuer of stablecoins (at least, as much as anyone can trust the US Dollar), because there should never be any material slippage for a dollar-backed stablecoin (other than normal inflation). Thus, for a customer holding XRP, the process would be to "swap" XRP for OGUSD (or USDT, RLUSD, or USDC) via Old Glory Swap (no fees), and then send the resulting stablecoin to anyone on the planet with a compatible wallet. That recipient could then swap such stablecoin to their preferred local stablecoin. Of course, that OGUSD recipient could also open an account at Old Glory Bank (international accounts coming soon) and then swap OGUSD for fiat or even back to XRP (for free).
Of course, if you don’t trust the US Dollar, then keep all of your assets on the chain and merely send XRP, BTC, ETH, etc. to someone via your own wallet. You don’t need OGB to do that.
We intend to hold a modest inventory of XRP in a liquidity pool to make small transactions more efficient. For large transactions, we'll rely on the spot price and market to settle. Our modest position in XRP is unlikely to ever impact the market price.
We're planning to have no minimum transfer amount for moving funds on- or off-chain through NxtGen. If you're activating a new XRP Ledger address, the network itself currently requires a 1 XRP base reserve.
Thankfully, the Basel III "endgame" was not adopted in the US, and we believe it should never be, because it is a globalist (European) standard that is not good for America and cash-straps American banks. Under America's capital rules, including the critical Tier 1 leverage ratio, digital assets (whether BTC, XRP, SOL, or ETH) are not considered Tier 1 capital. We do not see this changing. There are many other reasons to hold digital assets on a bank’s balance sheet (including as a liquidity pool), but they will not count as Tier 1 capital.
No regulator needs to approve our NxtGen dashboard, Old Glory Swap, Freedom Offramp, or crypto lending. For our stablecoin, the effective date of the GENIUS Act is January 18, 2027, so we will need to comply with the GENIUS Act, as we have always intended and made clear in all of our public filings. Under the GENIUS Act, and because we are a state-chartered bank, the great Oklahoma State Banking Department will be our primary regulator for our stablecoins.
Cryptocurrency vs. CBDC
It is critical to understand the distinction between cryptocurrency and CBDC. It can be easy to confuse the two.
While both operate digitally, the key distinction lies in who controls them and what that means for personal financial autonomy.
On January 23, 2025, President Trump issued an executive order entitled “Strengthening American Leadership in Digital Financial Technology.” In this order, he set out “five high-level policy objectives:
- Protecting the lawful use of blockchain networks, participation in mining and validation, and self-custody of digital assets without unlawful censorship;
- Promoting dollar-backed stablecoins;
- Ensuring fair and open access to banking services;
- Providing “regulatory clarity” for digital assets based on “well-defined jurisdictional regulatory boundaries,” and
- Prohibiting Central Bank Digital Currencies (“CBDC”).
So, what’s the difference?
CBDCs vs. Cryptocurrencies: Who Controls Your Money?
CBDCs are government-backed digital currencies issued by central banks, while cryptocurrencies operate on decentralized networks. Supporters of CBDCs argue they improve efficiency and security, while critics warn they could lead to increased government control over individual financial freedom. On the other hand, cryptocurrencies offer a free-market alternative, though they come with their own risks and volatility.
Ultimately, the decision of whether to embrace or reject either system should be left to the individual investor – not dictated by the state.
Old Glory Bank has always taken the position that CBDCs are not likely to be implemented in the United States of America as the Federal Reserve cannot designate digital currency as "legal tender" under Section 31 U.S.C. 5103. Digital Dollars would be outside what Congress intended when it enacted this statute, especially considering the history of this statute back to 1884. Fortunately, the current chairman of the Federal Reserve also shares our view and already acknowledged on March 20, 2021, that the Federal Reserve could not issue digital currency without Congress enacting legislation. In this regard, we do not believe that a Republican House or the Senate will support this legislation. Of course, this position was even before President Trump’s express Executive Order prohibiting CBDC which further makes it apparent that a CBDC is neither likely nor possible in the United States.